
A decade ago, India’s tech story was about services: code written cheaply and exported well. Today it is about infrastructure and invention. The country runs the world’s largest real-time payments system, fields one of the planet’s three largest startup ecosystems, has landed spacecraft near the lunar south pole at a fraction of conventional budgets, and is spending billions to become a serious semiconductor nation. This article maps the full picture of India technology — the achievements, the structural shifts, and the friction points ahead.
UPI: the payments system that quietly rewired a civilisation
No technology product in modern history has scaled the way India’s Unified Payments Interface has scaled. UPI processes tens of billions of transactions every month across hundreds of millions of users — from street vendors in tier-3 towns to e-commerce giants — and by mid-2020s run-rates it had crossed more than eighteen billion monthly transactions, a dominant share of the world’s real-time transaction volume by several international comparisons. The structural trick was interconnection: the state built the rails, private banks and apps compete on top of it, and interoperability kept switching costs near zero. The results are visible everywhere: merchant lending flows ride on those rails, subscription businesses grow off bank networks instead of plastic, and neighbouring countries — Singapore, UAE, France, Sri Lanka, Mauritius and others — have begun linking their systems into the same network.
The startup ecosystem: from copycats to categories
India’s startup story of the 2010s imported Western playbooks. The 2020s are different: India-built models are now followed abroad rather than copied from above. Three case studies make the point:
- Quick commerce built for density. Indian firms pioneered ten-minute grocery delivery at unit economics their American counterparts still wrestle with — because Indian urban density, labour marketplace and payment rails suit the model.
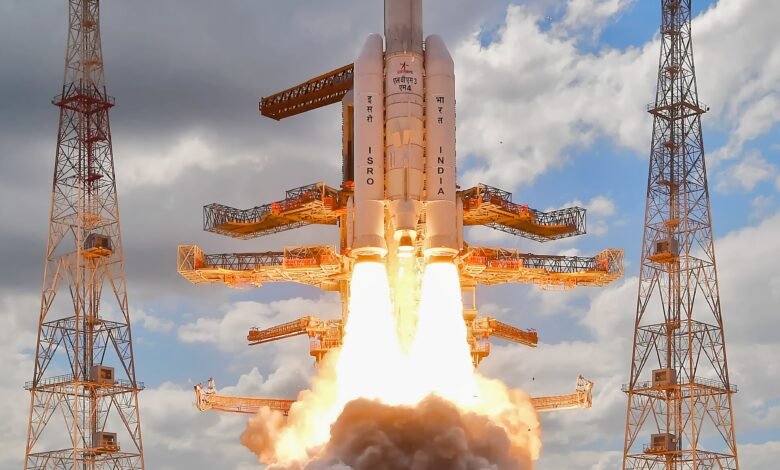
- Space at cost. Chandrayaan-3’s landing near the lunar south pole in August 2023 — achieved for a reported budget lower than many feature films — and the Space missions that follow accelerate a private space industry now exporting launch services.
- Global capability centres. Thousands of multinationals operate engineering and research centres in India, staffed by local talent — increasingly owning core product and AI work rather than back-office support. Bengaluru is today a genuine co-headquarters city for global software.
India’s edge is no longer cost. It is scale, density and the depth of an installed digital base no other market can assemble.
The Crescent World
The semiconductor bet
In semiconductors, India is executing its most ambitious industrial policy in decades. The India Semiconductor Mission has attracted tens of billions of dollars across announced projects: assembly-and-test plants at Sanand (Gujarat) and Jagiroad (Assam — the first mega project of its kind in the northeast), a large-scale fab under construction near Dholera led with Tata, and a growing pipeline of design partnerships. India already supplies a big share of the world’s semiconductor design talent; the goal is to own the manufacturing layer too. The path demands patience — fabs take years, yields matter, and execution risk in the industry is deep — but the direction of policy and capital has shifted from aspiration to contracts.
AI in the multilingual mode
India’s AI supercycle differs from the Western one in one decisive respect: language and scale. Indian firms and labs are building models trained on its twenty-plus official languages and their vernacular internet, directly addressing hundreds of millions of users global AI products were not designed for. Backed by the IndiaAI Mission’s public compute buildout and by government service AI in welfare, agriculture and multilingual public service delivery, the country is betting that AI adoption rates, not frontier model trophies, determine economic returns. Given India’s demographic of first-internet consumers, that bet is not naive — it is the natural choice of the market’s shape.
The compounding effect deserves attention too. India’s digital public infrastructure — identity, payments and consent-based data exchange running at population scale — is now exported as a working reference model: several countries have adopted or adapted elements of it, multilateral institutions present it as a development template, and its layers create a distribution surface no single private platform could replicate. For global investors, the significance of the tech story is precisely what it was for the payments story: the winner here is the networked system itself, and every POS terminal, startup, fab and frontier model adds another node to a platform that will carry the next decade of Indian technology outward.
Frictions that temper the story
- Hardware dependence. Cloud capacity and capital equipment still lean heavily on foreign suppliers, which shapes implementation speed and negotiating power.
- Regulatory flux. India’s data-protection framework remains young; compliance practice is being defined in real time.
- Talent churn. Wage inflation in tech hubs is severe, and the attrition economics of scaling playbooks matter more each year.
The trajectory, though, is unmistakable: from outsourcing to infrastructure, from imitation to invention. If the semiconductor buildout keeps its schedule and AI adoption follows India’s payments curve, the country that wrote the world’s code may well be one of the few that owns its digital layer outright.
Join the convo. Which is the bigger story of India’s decade — UPI, AI, Chandrayaan or the chip bet? Cast your top pick in the comments, and share this article with someone who tracks Indian tech.
Lead image: The LVM3 rocket carrying Chandrayaan-3 lifting off from Sriharikota (July 2023). Photo: ISRO, via Wikimedia Commons (GODL-India licence; edited version by UnpetitproleX).